
Thailand has signed an international agreement allowing tax information to be exchanged in support of the global minimum tax regime for major multinational groups.
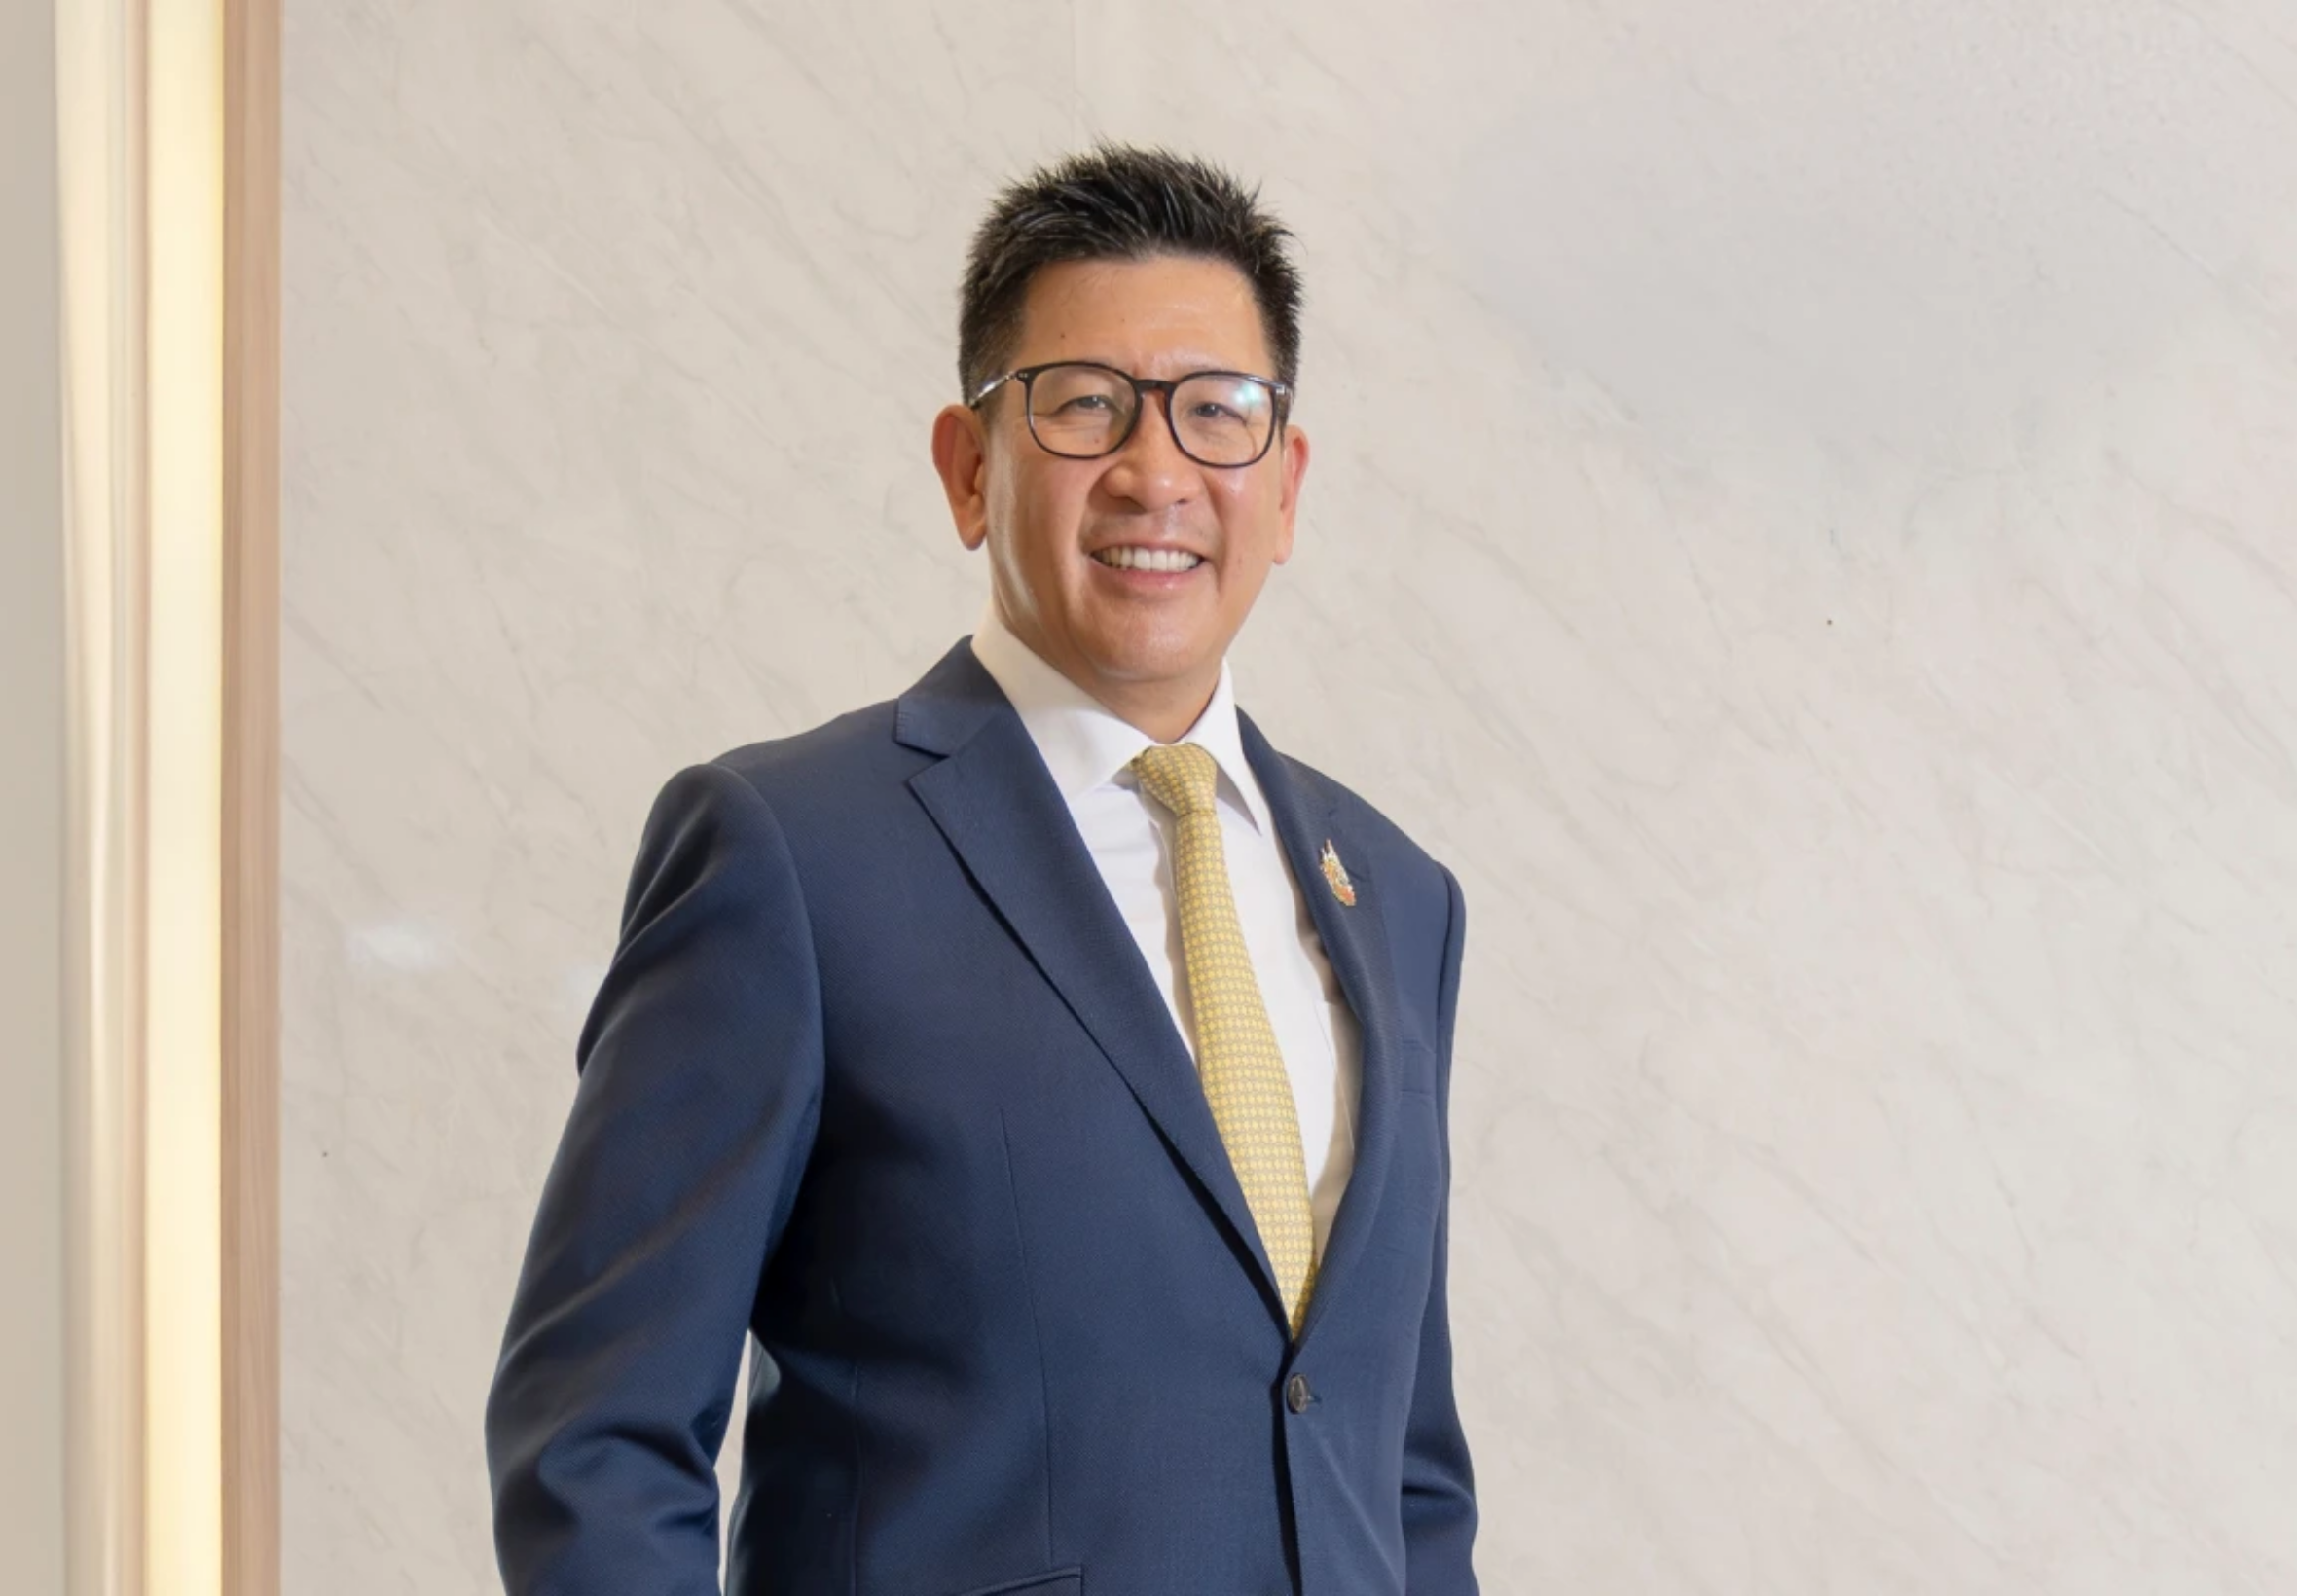
Finance Minister Ekniti Nitithanprapas signed the GloBE Multilateral Competent Authority Agreement (GloBE MCAA), the Organisation for Economic Co-operation and Development.
The move follows a Cabinet resolution on 16 June approving Thailand's participation, according to Revenue Department director-general Somsak Ananwat.
Information exchanges due from 2027
The agreement provides the framework for Thailand to exchange GloBE Information Returns, known as GIRs, with other signatory jurisdictions. Thailand is scheduled to begin its first exchanges of these returns by December 2027.
Mr Somsak said signing the agreement was an important step in preparing for information exchanges and should help strengthen transparency and confidence in Thailand's tax system.
The mechanism is intended to make compliance easier for multinational enterprises, or MNEs, by avoiding the need to file duplicate information sets in several countries.
Who falls under the top-up tax
Thailand's top-up tax applies to MNEs whose ultimate parent entity has consolidated financial statement revenue of at least 750 million euros in at least two of the previous four accounting periods.
It applies where a large MNE's effective tax rate, or ETR, in a jurisdiction in which it operates is below 15%. In such cases, the group is required to pay an additional amount to bring the ETR up to 15%.
Thailand passed its top-up tax emergency decree in 2024. It was published in the Royal Gazette on 26 December 2024 and took effect for accounting periods beginning on or after 1 January 2025.
The framework has three collection mechanisms. The first is a domestic minimum top-up tax, enabling Thailand to collect top-up tax on the profits of an MNE group operating in the country before another jurisdiction can impose the tax.
Under the income inclusion rule, a parent company in Thailand may have to pay top-up tax on profits of its foreign subsidiaries if the jurisdiction where they operate has an ETR below 15%.
The undertaxed profits rule serves as a backstop mechanism for collecting top-up tax from an MNE that still has outstanding top-up tax liabilities.
Join the discussion? 
17 September 2026
Recommended Comments
Create an account or sign in to comment